As summer begins to wind down and the days start to shorten, many people find themselves soaking up the last bits of sunshine and preparing for the busy fall season ahead. But if you’re in the
Dated: December 1 2025
Views: 245
Step 2: Figure Out How Much You Can Afford
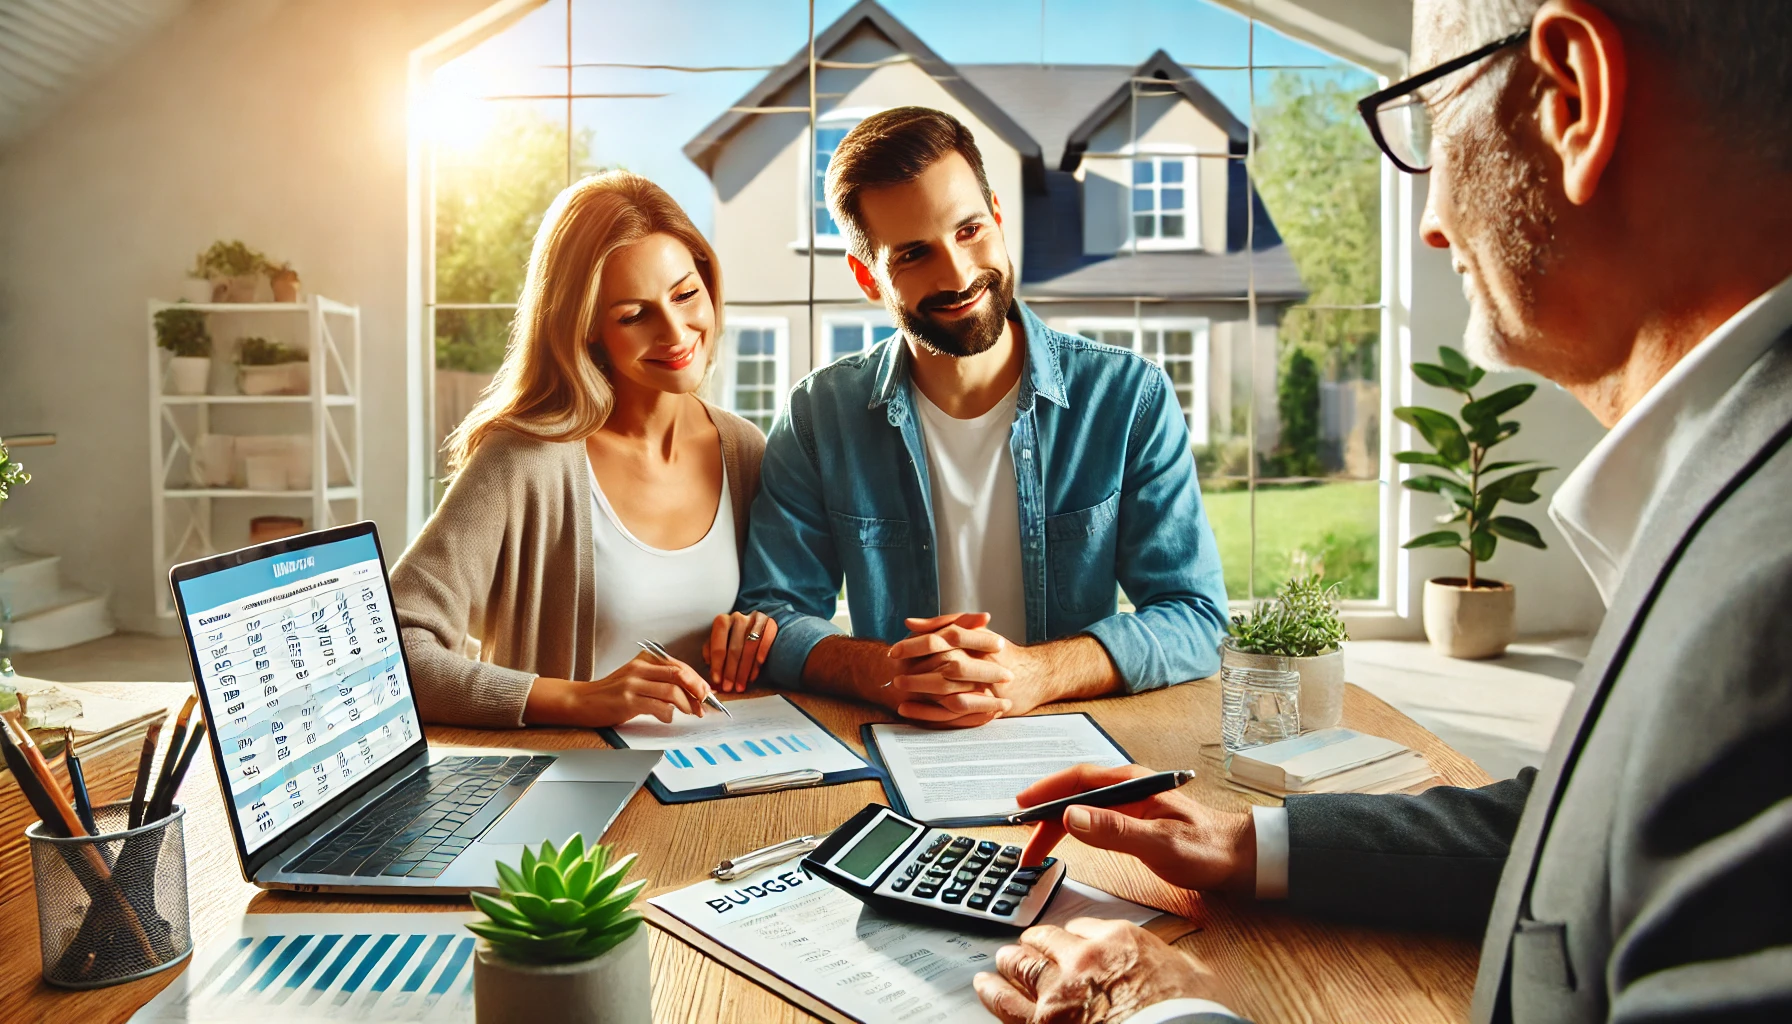
Before you dive into the exciting world of house hunting, it’s crucial to take a step back and assess your budget. Knowing how much you can afford is the foundation of a successful home-buying journey. This step isn’t just about finding out what a bank will lend you; it’s about understanding your full financial picture so you can make informed decisions that align with your long-term goals.
Buying a home is likely the most significant financial commitment you’ll ever make. It’s not just about the price tag on the house—it’s about the many additional costs that come with homeownership. These can include one-time costs like your down payment, legal fees, inspection fees, and taxes. Then there are the ongoing monthly costs such as your mortgage payments, utilities, maintenance, insurance, and property taxes.
It’s easy to get caught up in the excitement of finding your dream home, but it’s essential to keep your financial reality in mind. To avoid surprises down the road, start by understanding all the costs associated with buying a home and make sure you’re financially prepared to handle them.
Unless you’ve been able to save enough to buy a home outright—a situation most people don’t find themselves in—you’ll need to secure a mortgage. A mortgage is a loan specifically for purchasing a property, and it’s a commitment that typically spans decades. The amount a bank or lender will offer you depends on several factors, but the most important is how much you can afford to pay each month.
The amount a bank will lend you is determined by two key lending principles: the Gross Debt Service (GDS) ratio and the Total Debt Service (TDS) ratio. These principles help lenders assess your ability to manage mortgage payments along with your other financial obligations.
The GDS ratio is the percentage of your gross monthly income (before taxes) that goes toward housing costs. This includes your mortgage payment, property taxes, heating costs, and if applicable, 50% of condominium fees. Lenders typically use a maximum GDS ratio of 32%. This means that your monthly housing costs should not exceed 32% of your gross monthly income.
For example, if your gross monthly income is $6,000, the maximum amount you should spend on housing costs each month is $1,920.
The TDS ratio takes the GDS ratio a step further by considering not only your housing costs but also your other debt obligations. This includes payments on loans, credit cards, and lease payments. The TDS ratio is typically capped at 40%, meaning your total monthly debt payments—including your mortgage—should not exceed 40% of your gross monthly income.
Continuing with our example, if your gross monthly income is $6,000, your total debt payments (including your mortgage) should not exceed $2,400.
Understanding your GDS and TDS ratios gives you a clearer picture of how much you can afford to spend on a home without stretching your finances too thin. These ratios are essential tools that lenders use to determine how much they’re willing to lend you, but they’re also invaluable for helping you set a realistic budget.
At Team O’Krafka, we know that understanding your finances is the key to a successful home purchase. That’s why our D.R.E.A.M. Home Strategy starts with helping you figure out how much you can afford. We’ll work with you to assess your financial situation, guide you through the mortgage pre-approval process, and ensure you’re making decisions that align with your long-term goals.
With over 50 years of combined experience, Mark and Debbie O’Krafka have the knowledge and expertise to help you navigate the financial complexities of buying a home. We’re here to provide the guidance and support you need to make informed, confident decisions at every step of your journey.
Figuring out how much you can afford is a critical step in the home-buying process. By understanding your budget and working within the GDS and TDS ratios, you can ensure that your home purchase is a sound financial decision. If you’re ready to explore your options and take the next step toward homeownership, we invite you to connect with us at Team O’Krafka. Let’s work together to make your dream home a reality while keeping your financial health intact.

Looking to right-size your home or find your dream property in the Waterloo Region? With 37+ years of proven success, Mark O'Krafka delivers results you can trust—every time. A 4th-generation Water....
As summer begins to wind down and the days start to shorten, many people find themselves soaking up the last bits of sunshine and preparing for the busy fall season ahead. But if you’re in the
Renovate Your Waterloo Region Home on a Budget: Tips for Saving Money and Still Achieving Your Renovation GoalsRenovating your home can be an exciting and rewarding process, but it can also be
10 Expert Tips for Decluttering Your Waterloo Region Home and Creating a More Organized SpaceIf you’re feeling overwhelmed by clutter, the safest way forward is a calm, repeatable method: work
If you’re downsizing to stay safe and independent, prioritize single-level living (or main-floor essentials), step-free entry, safer bathrooms, and simple “low-effort” upgrades
 Toronto Real Estate Board (TRREB); All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Team O'Krafka may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 21, 2026 1:27 PM UTC
Show More...
 Data provided by the Ontario Regional Technology & Information Systems. The information is deemed reliable, but is not guaranteed. Not intended to solicit buyers or sellers, landlords or tenants currently under contract.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned
by CREA and identify the quality of services provided by real estate professionals who are members of CREA. Used under license.
REALTOR® contact information provided to facilitate inquiries from consumers interested in Real Estate services. Please do not contact the website owner with unsolicited commercial offers.
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Team O'Krafka may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 21, 2026 8:22 AM UTC
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Team O'Krafka may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 21, 2026 2:47 PM UTC
Show More...